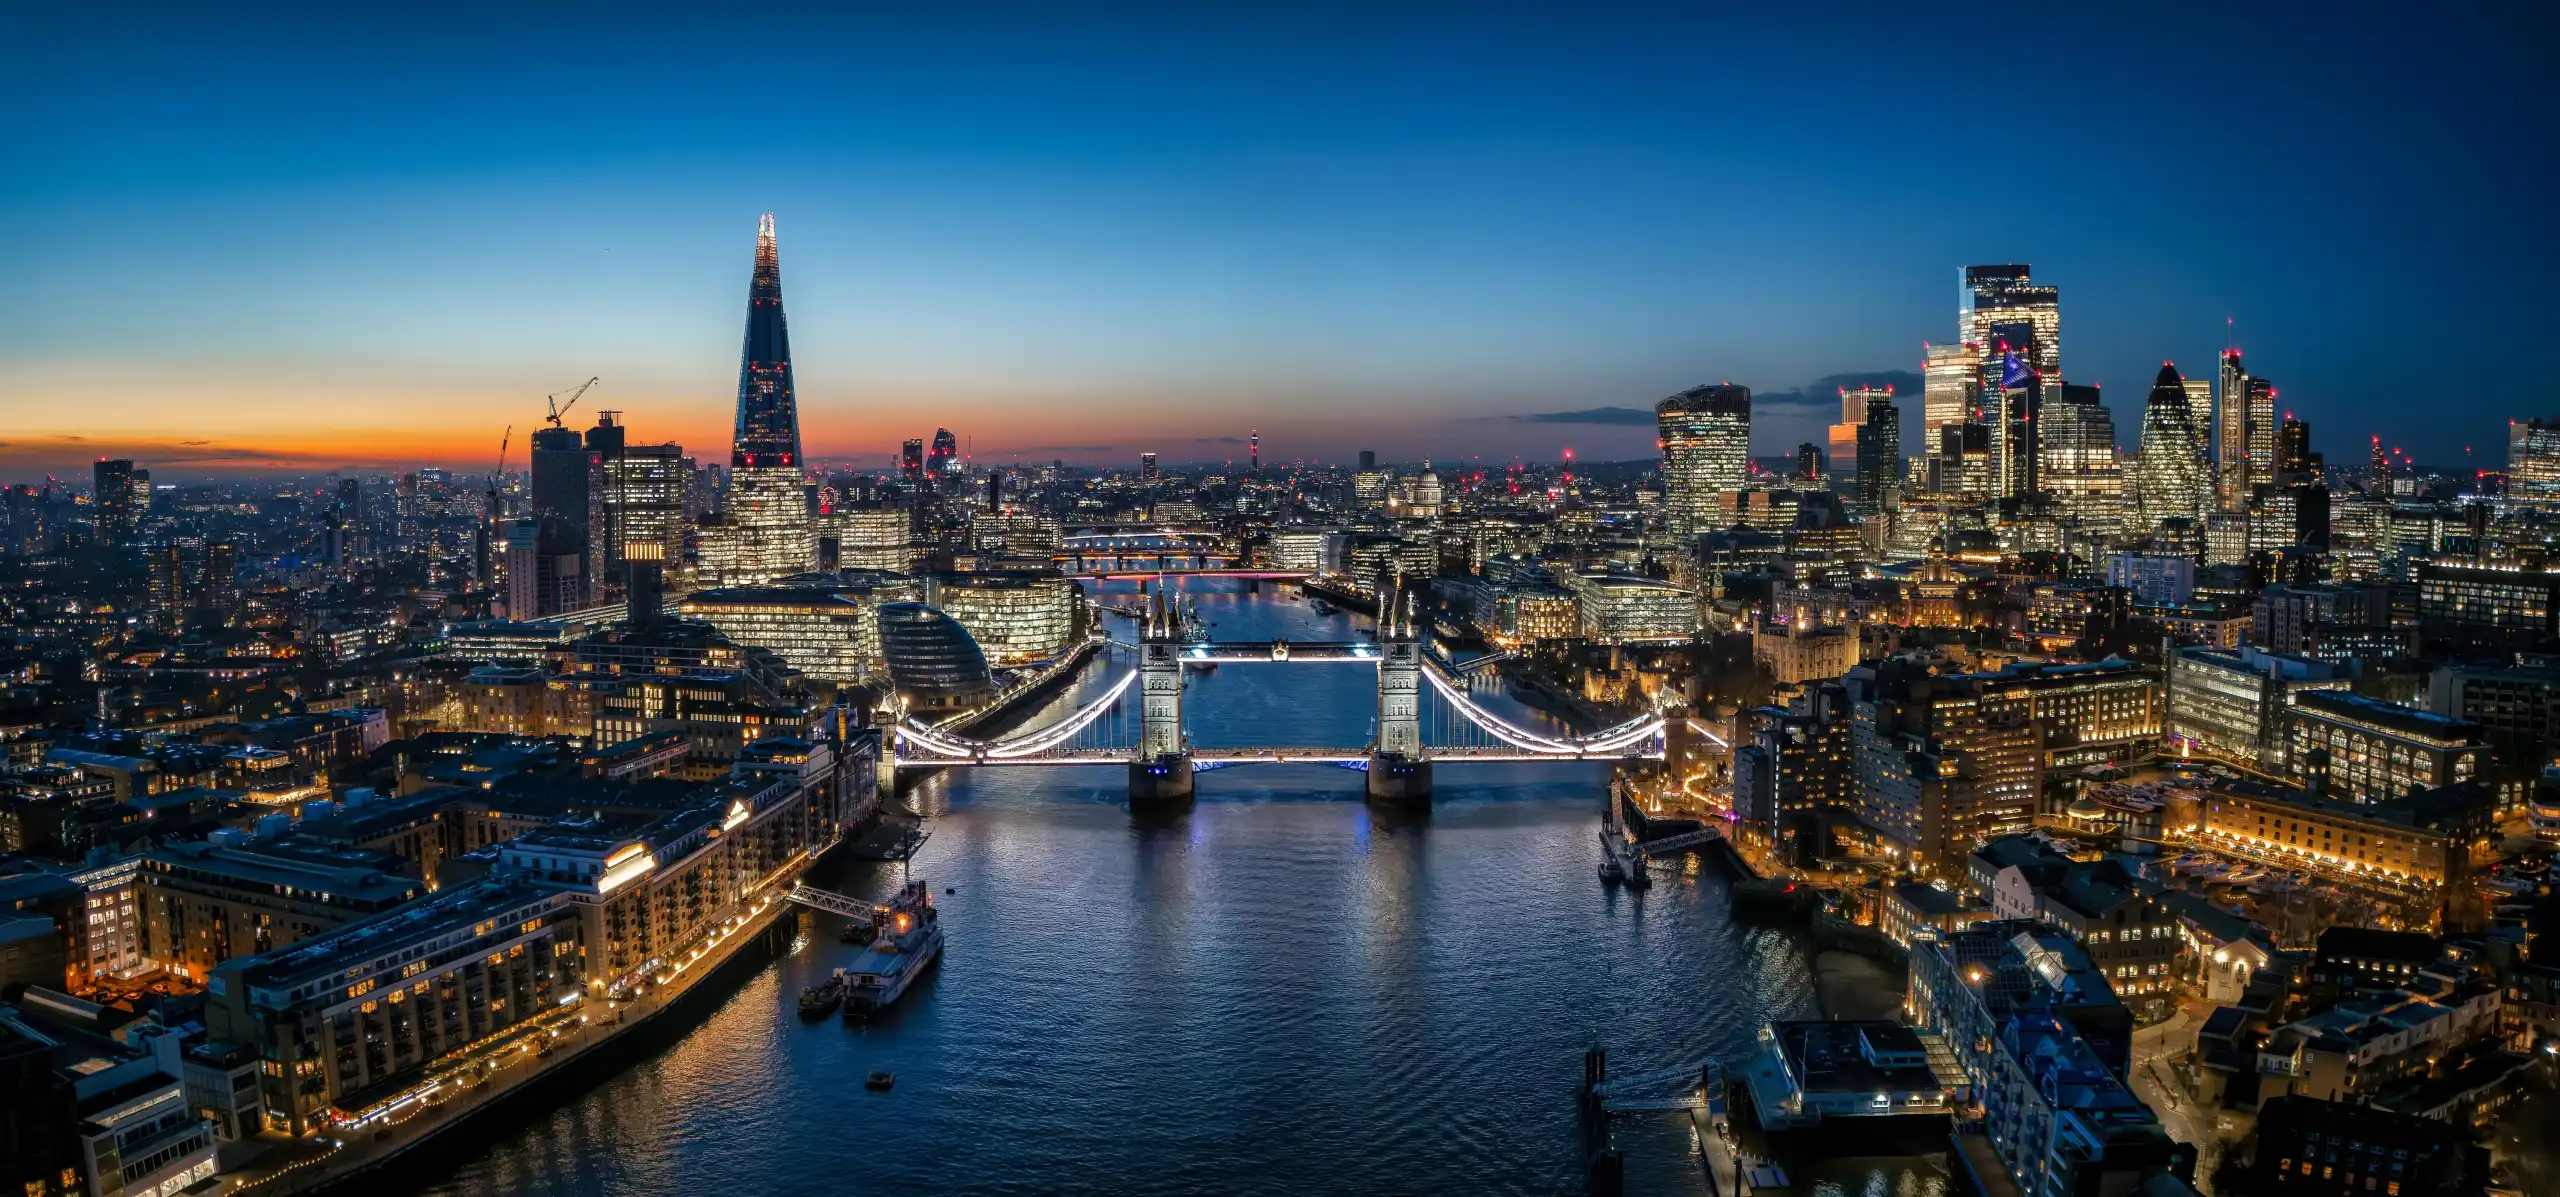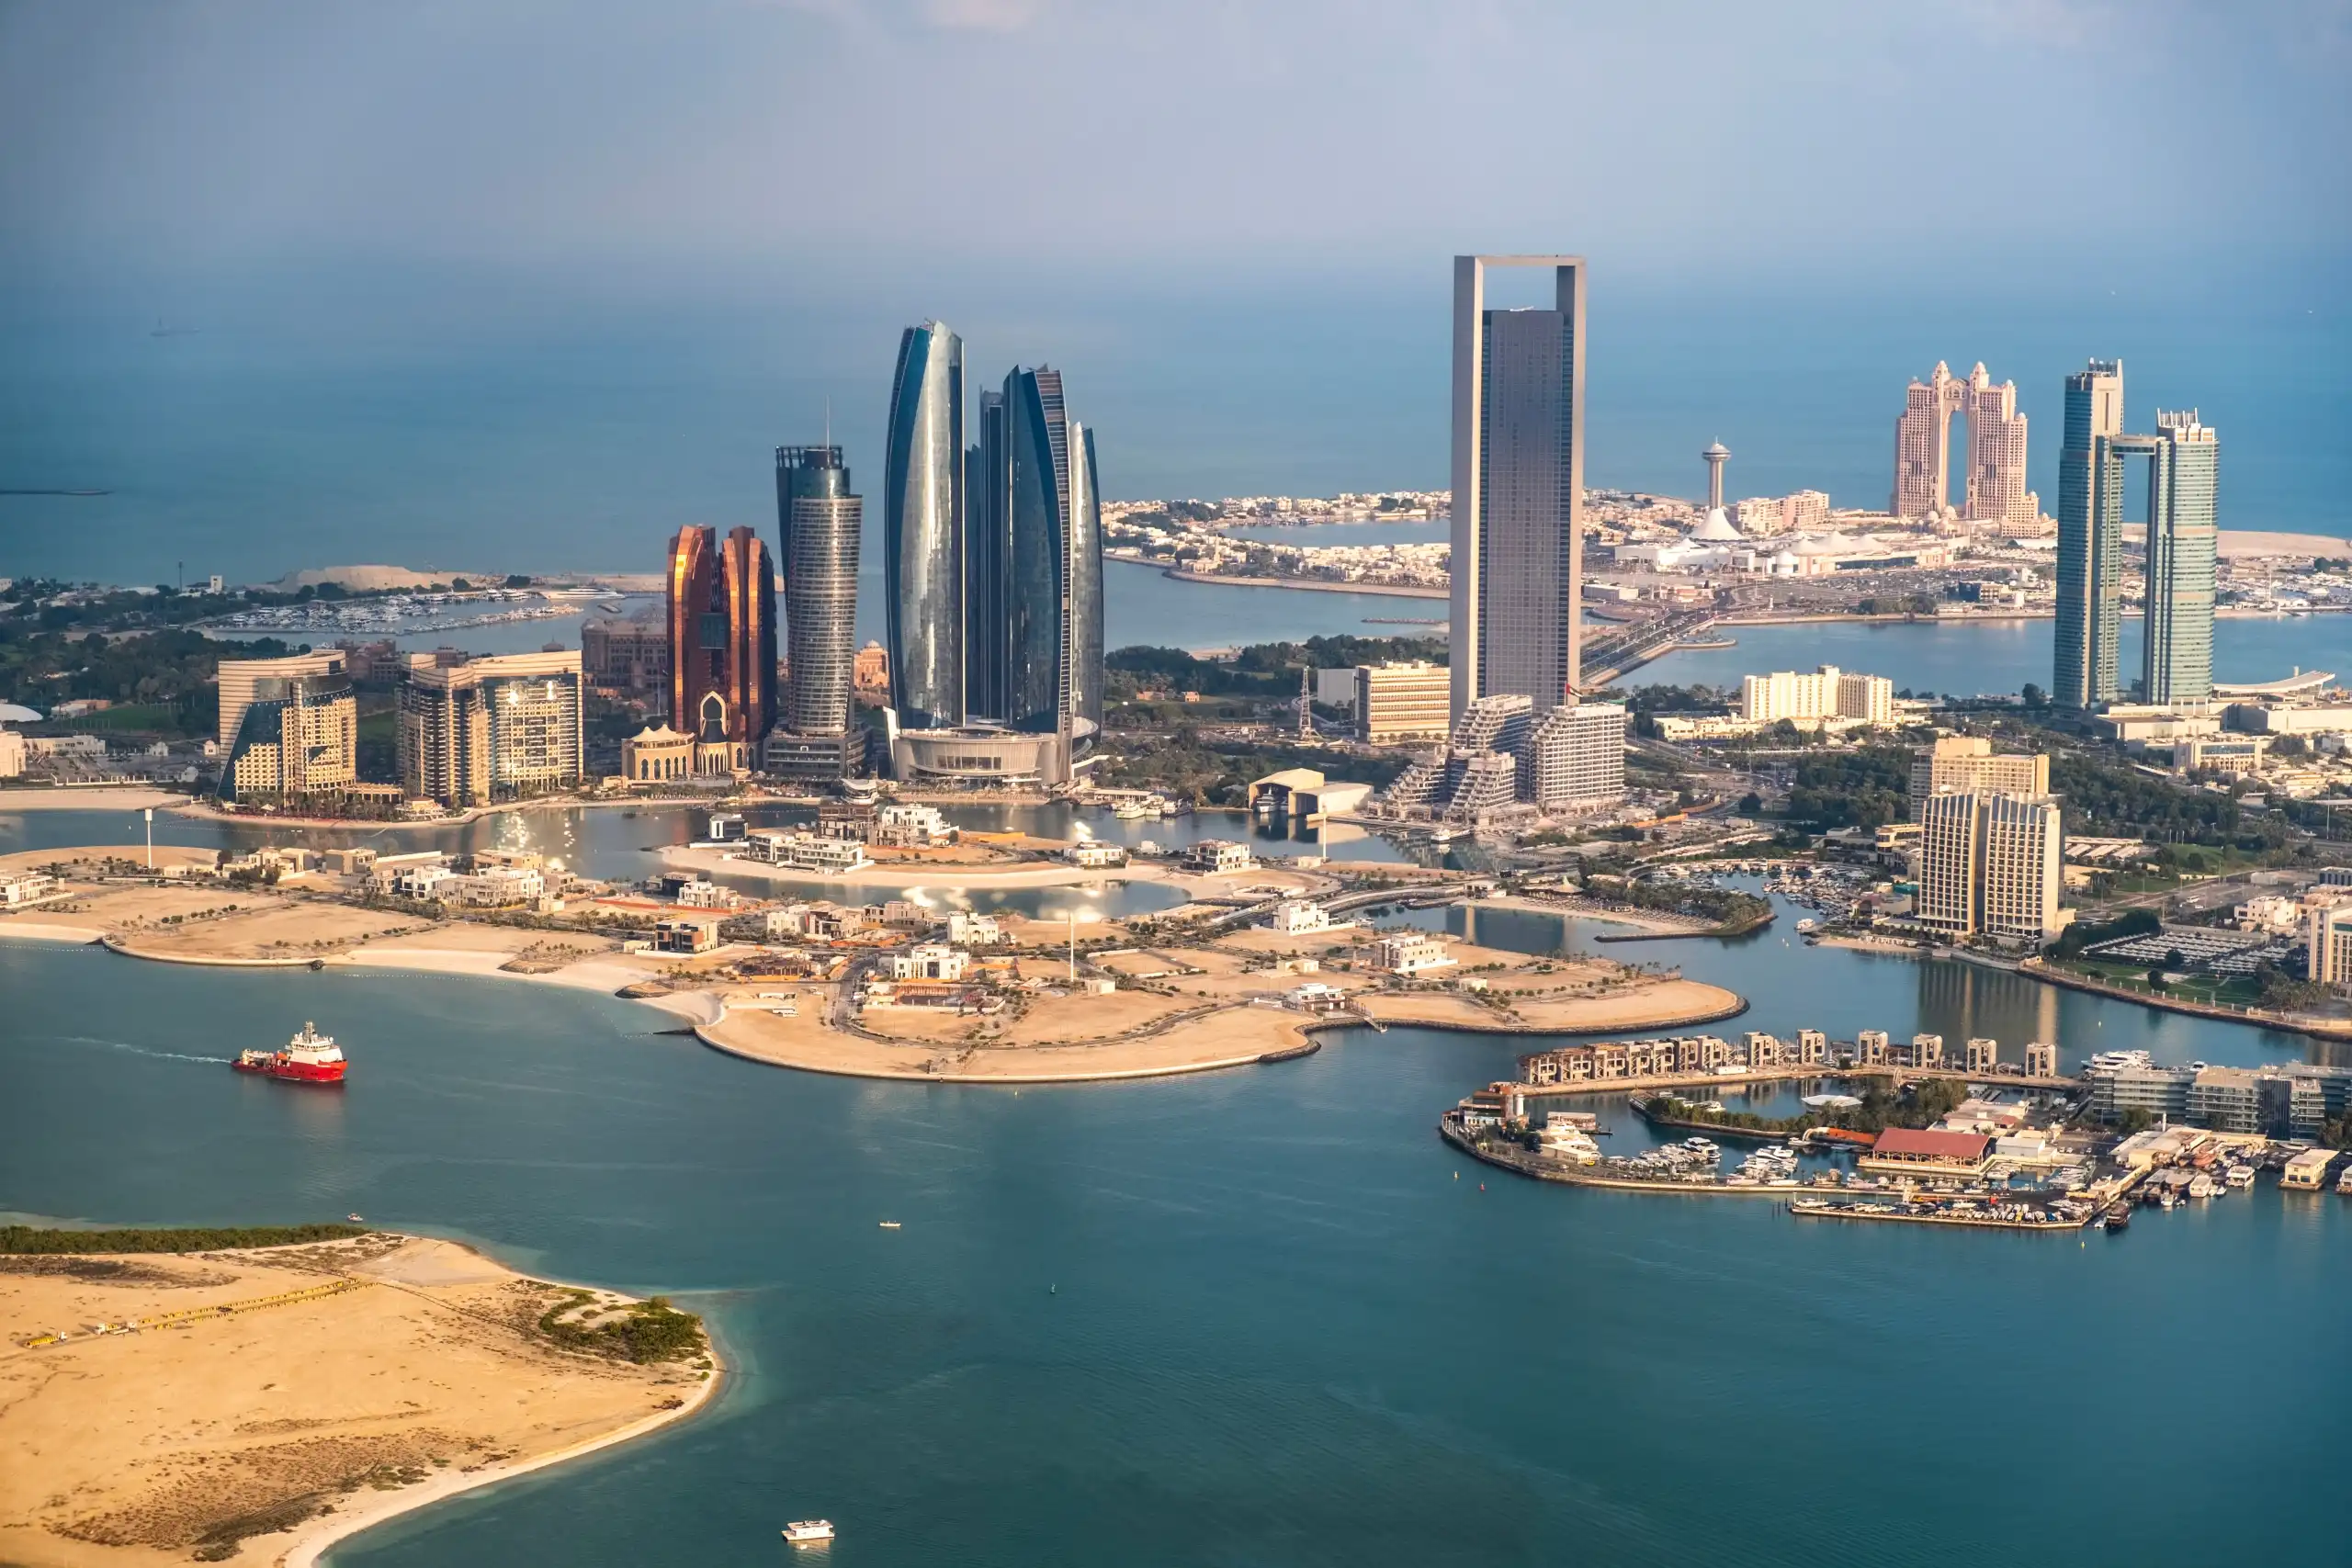
UAE ResidentialReal Estate - Dubai & Abu Dhabi Market Positioning, Risk and Opportunity
ONE GLOBAL ADVISORY | MARKET INTELLIGENCE
Dubai & Abu Dhabi: Market Positioning, Risk and Opportunity
October 6, 2026
Written by Kelly Robinson
Founder, One Global Advisory NYC | UAE
Co-Founder, Compass Global Division
Global Head of Business Development
Key Findings
Dubai and Abu Dhabi are in different phases of the residential cycle. Dubai’s latest complete month shows lower prices and materially lower transaction activity than a year earlier. Abu Dhabi’s latest comprehensive official report shows strong sales, rental and repeat-sale price growth, with unusually high off-plan concentration.
- -4.0% Dubai residential price index, YoY, Sep. 2026
- +64.6% Dubai residential price index, five-year change
- -43.5% Dubai registered property sales, YoY, Sep. 2026
- +1.8% Dubai ready-property index, YoY, Sep. 2026
- AED 70.4B Abu Dhabi residential sales, H1 2026
- 89% Abu Dhabi residential sales value that was off-plan
The contrast is material. Dubai’s current adjustment is occurring after substantial five-year appreciation. Abu Dhabi’s current growth is being recorded alongside a market structure dominated by off-plan sales and concentrated among a limited number of developers and projects.
Dubai: The Current Correction
Dubai registered 11,479 property sales in September 2026, down 43.5% from September 2025 and 5.9% from August. Median registered price per square foot was AED 1,657, down 2.5% year over year.
The mix-adjusted PIX residential index was down 4.0% year over year and 0.5% month over month. Apartments were down 4.5% year over year and villas 1.2%. The same index remained 64.6% above its level five years earlier.
Transaction activity has therefore declined much more sharply than registered pricing. The latest data show a correction from a substantially higher five-year price base, not a return to 2021 pricing.
September’s Decline Was Highly Concentrated
A residential-only dataset recorded 10,108 home sales in September, 1,055 fewer than in August. Azizi Venice alone recorded 1,049 fewer registrations. Excluding that development, the rest of Dubai recorded 9,654 home sales versus 9,660 in August.
Ready-home transactions increased 8.3% during the month, while off-plan transactions declined 15.7%. The annual comparison remained much weaker: September residential-only sales were 46.9% below September 2025.
These figures establish that the September month-over-month decline was concentrated, while the year-over-year contraction remained broad and substantial.
Geopolitics and Demand
The regional conflict disrupted trade, tourism and aviation. CBRE reported softer Dubai residential demand, lower transaction activity and easing pricing pressure during Q2 2026. UAE hotel occupancy and revenue per available room also declined sharply year over year through June.
In September, Emaar Chairman Mohamed Alabbar told Reuters that occupancy at the company’s Dubai hotels had been approximately 83% before the war, fell to 20% to 25% during the conflict and had recovered to about 60%. He said Emaar property sales remained below pre-war levels and were approximately 50% below what he described as normal.
Emaar’s collection rate remained comparable with 2025. The reported deterioration was therefore more visible in new sales and hospitality than in collections from existing Emaar purchasers.
The conflict arrived after a record 2025, when Dubai recorded 205,400 residential transactions worth AED 544.2 billion. The geopolitical shock therefore coincided with a market that had already completed five years of strong price appreciation and entered 2026 with a large registered development pipeline.
Supply: Pipeline Versus Delivery
Knight Frank’s registered projects pipeline indicated that more than 160,000 residential units could enter Dubai in 2026. Apartments represented 85% of forecast supply, villas 14% and branded apartments 1%.
Historical delivery has been lower than scheduled pipeline figures. Approximately 64% of homes scheduled for completion in 2025 were delivered on time, equal to roughly 39,700 units. Knight Frank reported an average of approximately 38,000 completed units per year over the preceding five years and a 20-year delivery rate of approximately 36,000 homes annually.
Actual completion activity increased in 2026. Dubai real estate project completions rose 39% year over year during H1, while the investment value of completed projects exceeded AED 111 billion, up 52%.
Ready Versus Off-Plan
Off-plan represented 65.6% of all registered Dubai property sales in September. Its share declined from 72.4% in June to 69.2% in July, 67.5% in August and 65.6% in September.
The September mix-adjusted ready-property index was up 1.8% year over year, while the off-plan index was down 1.6%. Residential-only data also show ready-home transactions increasing 8.3% from August while off-plan transactions declined 15.7%.
Ready-home transaction value rose from AED 6.44 billion in August to AED 9.04 billion in September. Projectory notes that the faster increase in value also reflects a more expensive mix of completed homes changing hands.
The September data establish greater relative resilience in completed property. Four months of declining off-plan share do not establish a permanent market rotation.
Secondary Property and Renovation
There is not sufficient market-wide evidence to state that buying, renovating and reselling Dubai property consistently generates excess returns.
For an individual completed property, acquisition price, transaction expenses, renovation expenditure, carrying costs and disposition costs can be measured against actual renovated and unrenovated comparable sales. Physical condition and interior finishes can be changed; location, view, floor, plot characteristics and many layout constraints cannot.
The current market data support a closer comparison of ready and off-plan assets. They do not establish renovation as a market-wide return strategy.
Abu Dhabi: Strong Growth, Concentrated Structure
Abu Dhabi’s latest comprehensive official market report covers H1 2026. Residential unit sales reached AED 70.4 billion, compared with AED 25.3 billion in H1 2025. Repeat-sale apartment prices increased 20% year over year and villa prices 12%.
The emirate recorded approximately 233,000 active residential lease contracts with a total value of AED 9.3 billion. New-lease prices increased 17% for apartments and 9% for villas. Within investment zones, new-lease prices increased 21% for apartments and 16% for villas.
Off-plan accounted for 89% of residential sales value and 82% of residential transactions. Ten leading developers accounted for 90% of primary off-plan sales, while ten projects represented 43% of residential unit sales.
Resident expatriates and non-resident foreign buyers together accounted for 70% of residential sales value. In the ready market, 61% of purchases were completed in cash.
Future Supply
Abu Dhabi had approximately 409,000 existing residential units in H1 2026. ADREC projects approximately 71,000 additional units through 2030, with deliveries expected to peak at approximately 21,800 units in 2028.
Six key districts are expected to drive 77% of projected incremental supply through 2030: Al Saadiyat Island, Al Reem Island, Yas Island, Zayed City, Khalifa City and Al Hudayriyat Island. Nine major developers account for 76% of the development-project pipeline.
Market Comparison
| Measure | Dubai | Abu Dhabi |
|---|---|---|
| Latest period used | September 2026 | H1 2026 |
| Price signal | PIX residential index -4.0% YoY; +64.6% over five years | Repeat-sale apartments +20% YoY; villas +12% |
| Transaction structure | Off-plan 65.6% of September registered sales | Off-plan 89% of H1 residential sales value; 82% of deals |
| Completed market | Ready index +1.8% YoY; ready transactions +8.3% MoM | 61% of ready-market purchases completed in cash |
| Forward supply | More than 160,000 units in registered 2026 pipeline; historical delivery materially below pipeline | Approximately 71,000 additional units projected through 2030 |
| Concentration | September MoM decline heavily affected by one large off-plan project | 10 developers = 90% of primary off-plan sales; 10 projects = 43% of residential unit sales |
What the Data Establish
Dubai is in a measurable residential correction. September’s mix-adjusted residential index was 4.0% below a year earlier, while remaining 64.6% above its level five years earlier. Transaction activity has declined substantially more than prices.
Dubai’s off-plan market still represents the majority of registered sales. At the latest complete month, however, ready property showed stronger year-over-year index performance and stronger sequential transaction activity than off-plan property.
Abu Dhabi’s latest official data show substantially stronger sales, rental and repeat-sale price growth. The same data also show that the market is heavily concentrated in off-plan sales, a limited number of developers and a limited number of projects.
Both emirates have substantial forward supply. Dubai’s historical completion record shows that registered pipeline is not equivalent to delivered inventory. Abu Dhabi’s regulator projects approximately 71,000 additional residential units through 2030.
The available data do not establish a single UAE-wide residential cycle. Dubai and Abu Dhabi currently show materially different price, transaction, supply and market-structure profiles.
Sources & Methodology
Dubai Data. Dubai Property Market Report, September 2026. Dubai Land Department registered transaction data. Data through October 2, 2026. https://datadubai.ae/report/
Property Index Dubai. PIX Residential Index, September 2026. Mix-adjusted residential price index computed from Dubai Land Department registered sales. https://www.propertyindex.ae/dubai-real-estate-price-index/2026-09
Projectory Research. Dubai Property Market September 2026: DLD Home Sales Report. Residential- only DLD registrations, excluding plots, whole residential buildings and non-sale transactions. https://projectory.ae/research/dubai-property-market-september-2026-dld-home-sales-report/
CBRE. UAE Real Estate Market Review, Q2 2026. https://www.cbre.ae/insights/figures/uae-real-estate-market-review-q2-2026
Reuters. Emaar sees Dubai hotel occupancy, now at 60%, recovering within a year. September 21, 2026. https://www.reuters.com/world/middle-east/emaar-expects-return-pre-war-occupancy-levels-dubai-hotels-next-12-months-2026-09-21/
Knight Frank. Dubai Residential Market Review Q4 2025, published February 2, 2026. https://www.knightfrank.ae/newsroom/article/2026/2/dubai-residential-market-review-q4-2025
Abu Dhabi Real Estate Centre (ADREC). Abu Dhabi Real Estate Market Report, H1 2026. Official registered sales, leasing, buyer composition and supply projections. https://adrec.gov.ae/en/news/press-29—adrec-releases-the-abu-dhabi-real-estate-market-report-for-h1-2026
Methodology Note
October 6, 2026 is the publication date. September 2026 is the latest complete Dubai reporting month used in this paper. H1 2026 is the latest comprehensive official ADREC reporting period used for Abu Dhabi.
Dubai sources use different transaction universes. Dubai Data includes all registered property sales in its monthly headline series. Projectory’s home-sales analysis excludes plots and whole residential buildings. PIX is a mix-adjusted residential index. Their transaction counts and price measures should not be treated as interchangeable.
Registered prices exclude service charges, agency commissions, DLD transfer fees, mortgage costs and other transaction expenses. Recent Dubai figures may revise as late registrations are recorded. Off-plan and ready transaction pools are not like-for-like samples.